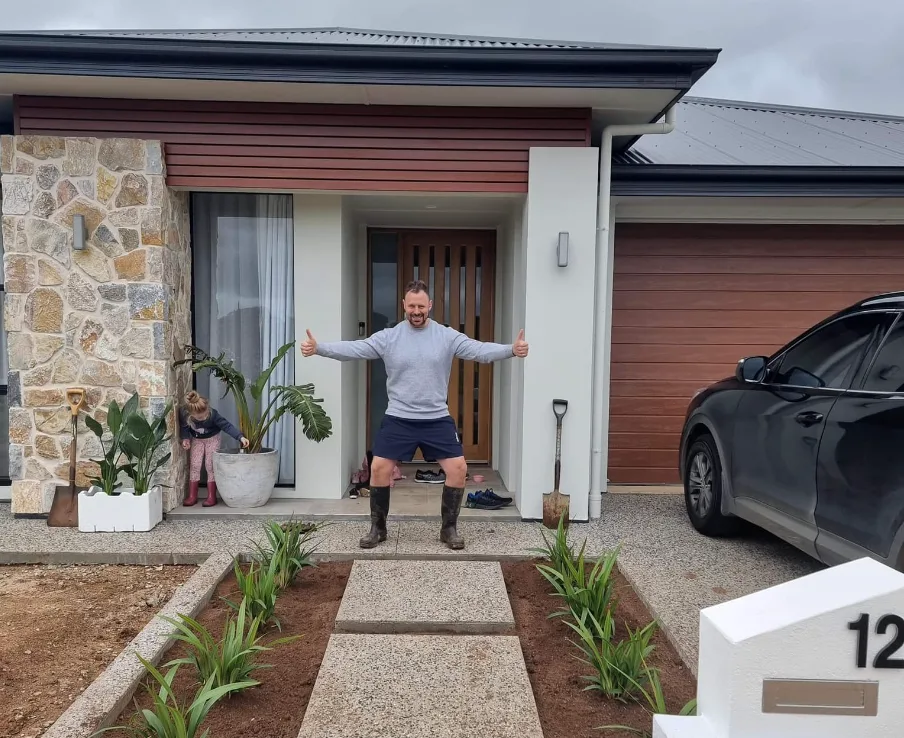
Serving Harkaway
Mortgage Broker Harkaway
Looking for a mortgage broker Harkaway households can talk to? Your Mortgage Broker Beaconsfield arranges home loans across this small Cardinia acreage suburb, from refinancing to construction finance, with advice grounded in local numbers.
Looking for a Mortgage Broker in Harkaway?
293 dwellings, $2,805 weekly median incomes, yet lenders treat Harkaway like any outer suburb. Our home page explains the cost.
Home Loans We Arrange in Harkaway
We arrange refinancing, first home buyer, investment property, construction and guarantor lending:
Refinancing Your Loan
Almost half of Harkaway dwellings are still being paid off, and refinancing those loans means testing your current structure against a wider panel rather than accepting whatever your existing bank automatically rolls you onto after a fixed rate quietly expires.
First Home Buyer Loans
Buying in Harkaway usually means a house on a good sized block, which pushes purchase prices beyond what a small deposit comfortably covers, so first buyers often weigh a guarantee or the first home owner grant against years more saving.
Investment Property Loans
Fewer than half of local homes are mortgaged and nearly half are owned outright, which gives established owners here real equity, and releasing some of it into a rental property is a conversation worth having before property prices move again.
Construction and Renovation Loans
Harkaway sits beside Cardinia's growth corridor, where dwelling approvals keep flowing, and building on a large local block brings progress payments, fixed price contract scrutiny and valuation timing into play, so construction lending here needs careful structuring from day one.
Guarantor Loans
A guarantee from parents who own their home outright, which describes nearly half of Harkaway households, can cover a deposit gap, though the guarantor's own property carries risk, so independent legal and financial advice comes before any documents are signed.
What Makes Financing a Harkaway Property Different
Every dwelling is a separate house, and very high incomes shape assessor outcomes:
No Apartments, Different Rules
Not one dwelling in Harkaway is an apartment, a statistical rarity that eliminates high density lending rules entirely but concentrates every application on house valuations, acreage boundaries and the sale evidence problem of comparing lifestyle properties against standard estate housing.
Four Bedrooms, Thick Evidence
Nearly seventy per cent of homes have four or more bedrooms, so family sized houses dominate the comparable sales a valuer relies on, which helps owners but unusual renovations or acreage improvements can leave the valuer short of evidence quickly.
An Equity Market First
More dwellings here are owned outright than carry a mortgage, forty seven against forty five roughly, which leans Harkaway toward equity conversations, so many appointments start with what an established home could support rather than what a purchase would cost.
Income Outruns Capacity
Median household income of $2,805 a week places Harkaway in the ninety eighth percentile statewide, so borrowing capacity rarely limits locals; the binding constraints are deposit size, valuation outcomes on acreage blocks and lender policies that misread self employed income.
Common Situations We See in Harkaway
Small suburb, specific files, each with a known fix:
What Could Equity Do
Established owners sitting on substantial equity ask what it could actually do, whether that means funding a renovation, helping adult children buy or buying a rental, and the answer starts with a current valuation rather than an old appraisal figure.
Does My Loan Still Fit
Households repaying about $2,307 a month, the local median, sometimes wonder aloud whether their structure still fits after years of life changes, and a proper review covers offset accounts, split loans and repayment frequency before anyone talks about changing lenders.
Business Income From Acreage
At over forty kilometres from the CBD, many residents commute into Melbourne while a growing share run businesses from acreage properties, and self employed files need trading statements organised the way assessors read them, not the way accountants file them.
Outgrowing the Family Home
Families with three point two people per household keep outgrowing four bedroom homes, so upgrading to a bigger home nearby raises the timing question, buy first and carry two loans briefly or sell first and rent somewhere awkwardly in between.
How it works
Our Process
Four steps, published openly, because knowing what happens after you hang up matters as much as the loan itself:
- 1
Speak to a Broker
It starts with a free conversation with Your Mortgage Broker Beaconsfield, who handles your file personally from first call to settlement, covering your goals, your income, existing debts and realistic timelines, and nothing about the call obliges you to take any further.
- 2
Capacity and Options Assessed
Capacity and options come next, meaning your serviceability gets assessed honestly against a panel of lenders sourced through our licensee, so you learn what is genuinely borrowable and which structures fit before any application is lodged with any lender anywhere.
- 3
Options in Writing
Options arrive in writing, because a recommendation you cannot re read is a recommendation you cannot weigh, so every structure, every lender choice and every cost gets documented plainly and you take as long as you need before deciding anything.
- 4
Application Through to Settlement
Application through to settlement is handled for you, with documents assembled correctly the first time, valuations chased, credit queries answered promptly and settlement dates watched closely because small delays compound into painful costs when a contract is on the line.
Why Choose Your Mortgage Broker Beaconsfield in Harkaway
A new brand has no history, so here is what can be verified instead, backed on our About page:
One Named Broker
You deal with one named, qualified broker, Your Mortgage Broker Beaconsfield, from the first phone call through to settlement, rather than being passed between a call centre, an online portal and whoever happens to pick up your file in any given week.
Fees Published Up Front
Fees and commissions are published upfront, not discovered later, so you can see what the service costs, how the broker is paid and what a lender pays before you commit to anything, which is how a transparent business should operate.
A Process You Can Read
The process is published with real timelines, so you know what happens after the first conversation, how long assessment typically runs and who is chasing the valuer, instead of ringing a big bank and hoping that somebody calls you back.
Worked Examples With Numbers
Worked examples with real numbers appear throughout this site, showing how structures perform over time, because a borrower who understands the arithmetic makes better decisions than a borrower who simply accepts whatever figure the first lender puts across the table.
Licensing and Compliance
Credit assistance is regulated; the protections and complaint path appear here:
Credit Representative Status
Credit representative status matters because Your Mortgage Broker Beaconsfield operates under an Australian Credit Licence held by [LICENSEE NAME], with Your Mortgage Broker Beaconsfield authorised as credit representative 370592, which means an established licensee supervises every credit activity this business provides to its clients.
Responsible Lending Obligations
Responsible lending obligations are not optional paperwork, they require a genuine assessment that your loan, and any proposed structure, is not unsuitable for your needs and objectives, and that you can repay it without substantial hardship in the foreseeable future.
Privacy and Your Data
Privacy and your data are handled under the Privacy Act, with your financial information shared only with the lenders and valuers needed to assess your application, never sold, never used for marketing, and never retained longer than the law requires.
How Complaints Work
Complaints work through a clear path, raise it with Your Mortgage Broker Beaconsfield first, receive a written response under the licensee's internal dispute process, and if it remains unresolved, take it to AFCA, an independent external dispute resolution service available free to you.
Getting a Better Rate on Your Harkaway Loan
The headline figure is one line; these levers usually matter more:
Structure Beats Headline
Structure beats headline every time, because an offset account, the right split between fixed and variable portions and a sensible repayment frequency quietly outperform a fraction of a percentage point saved on a poorly organised loan with the wrong features.
Valuations and Insurance Thresholds
Lenders mortgage insurance deserves a very hard look, because a strong valuation can push your loan comfortably below the insurance threshold and remove a premium worth many thousands of dollars, which is why we order valuations strategically rather than automatically.
Equity Changes the Conversation
Existing equity changes the refinancing conversation entirely, since Harkaway homes bought years ago have often appreciated well past the original purchase price, and that gap can fund a restructure, remove insurance or support a better positioned application with the panel.
Fixed Rate Expiry Timing
Fixed rate expiries create the quiet trap, because a loan that suited your life three years ago rolls onto a default structure nobody reviewed, and a scheduled review before expiry catches it while you still hold all the bargaining power.
Where we work
Areas We Service
Based in Beaconsfield, Your Mortgage Broker Beaconsfield works across Cardinia, including Guys Hill, Officer and Officer South, all a short drive from Harkaway.
Questions answered
Frequently Asked Questions
Do you meet clients in Harkaway or work remotely?
Both. Many conversations happen by phone or video, which suits busy households, but we are based in nearby Beaconsfield and can meet face to face.
What is the median price in Harkaway right now?
With only 293 dwellings here, sales are too infrequent for a reliable median figure, so we walk you through recent local sale evidence instead.
How long does home loan approval take?
Most straightforward purchases reach conditional approval within days and settle over four to six weeks; construction finance runs longer because progress payments stretch the timeline.
Can you help with a Harkaway investment property?
Yes. Established owners hold substantial equity, and we can assess whether releasing some equity stacks up for a rental purchase, alongside your accountant for tax.
Do you charge a fee for your service?
In most cases no, because lenders pay commission on settled loans; where a fee applies it is disclosed in writing under our published fee structure.
Which lenders do you have access to?
A wide panel: major banks, smaller banks and non-bank lenders, sourced through our licensee and matched to your file rather than one institution's product list.
Mortgage broker for Beaconsfield and the suburbs around it
Get in Touch
Ring Your Mortgage Broker Beaconsfield on [TRACKING_PHONE] to talk through your Harkaway home loan with a local.